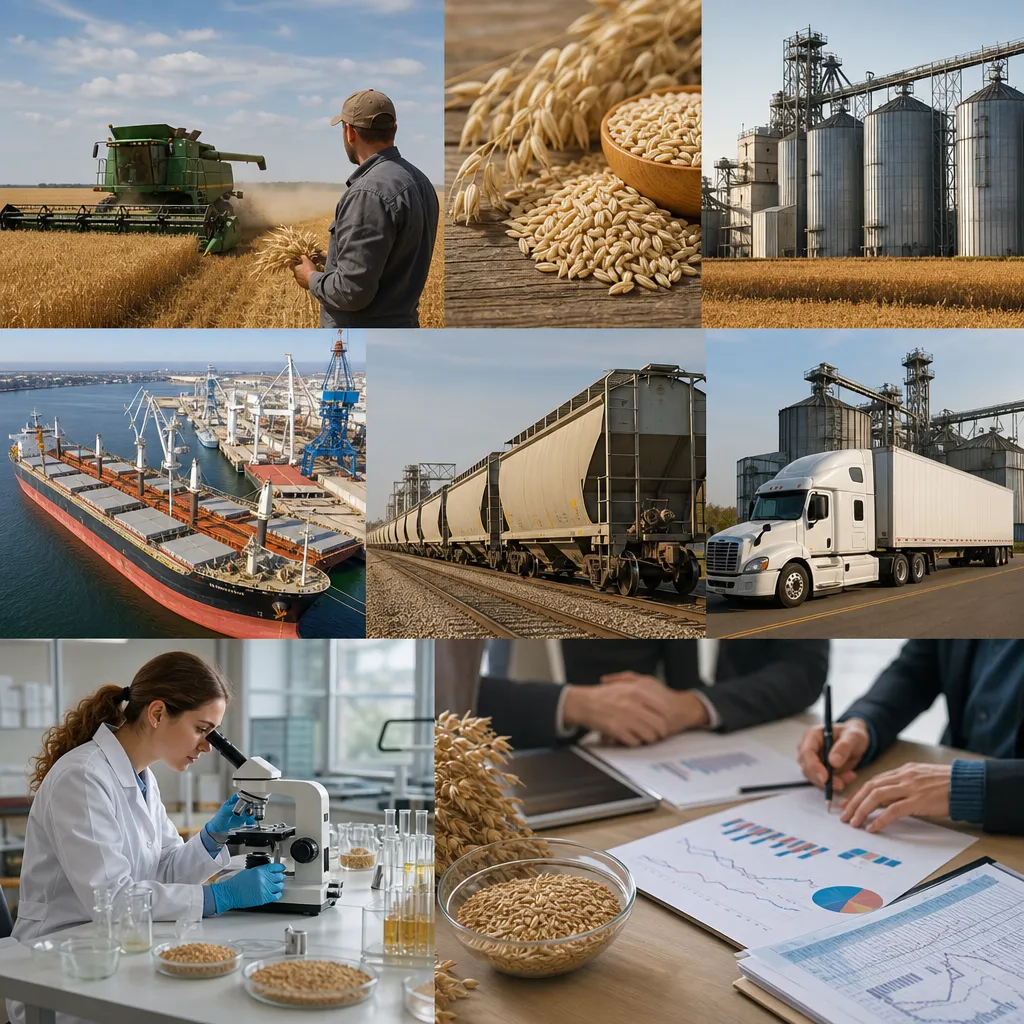
In the United States, oat trading sits at the intersection of a relatively small futures market and a highly regional physical grain business. Oats are grown mainly in the northern Plains and Upper Midwest, consumed by food processors, feed users, and export buyers, and priced through a mix of benchmark futures, local cash bids, freight, and quality premiums or discounts. Anyone trying to understand the US oat market needs to separate financial pricing from physical grain movement: the benchmark is the CME oat futures market, but actual farm and commercial trades happen through elevators, cooperatives, mills, feed buyers, and merchants. A practical trading guide therefore starts with geography, then price formation, then the real mechanics of buying, selling, hedging, and checking market information.
What the US oat market is and where it operates
The US oat market is the domestic market for oats grown, processed, fed, imported, exported, and traded within the United States. It is not centered in one single location. Instead, it operates across several linked layers:
- Production regions: especially the northern Plains and Upper Midwest, where oats fit rotations and shorter growing seasons.
- Cash markets: local elevator and processor bid markets in producing states.
- Futures market: the CME Group oat futures contract, used as the main US futures benchmark.
- Import and export channels: cross-border movement with Canada is particularly important, while some oats and oat products also move through domestic processing and export supply chains.
In the US, oats are typically discussed in US dollars. Futures are commonly quoted in cents per bushel, while many physical and commercial transactions may also be evaluated in dollars per bushel or dollars per ton, depending on the buyer and contract structure. Because units can vary between futures, elevator bids, and freight-based commercial deals, traders should always confirm the quotation basis before comparing prices.
The US role in oat production, consumption, and trade
The United States is an important oat consumer, especially through the food sector, but it is also closely tied to Canadian supply. That matters for price discovery. US oats are used in several channels:
- Food processing: oatmeal, rolled oats, cereals, snack ingredients, and other food uses.
- Animal feed: especially where oats are competitively priced relative to corn or other feed grains.
- Seed and on-farm use: including cover crop and forage-related uses in some areas.
Because the US market is integrated with Canadian production and movement, domestic pricing is not driven only by US crop conditions. North American oat balances matter. If supplies tighten in key producing areas, processors and merchants may need to bid more aggressively for nearby coverage. If imported supply is ample, that can cap local rallies in some consuming regions.
Geography also matters. Producing-area cash markets may trade at a discount or premium to the futures market depending on harvest pressure, storage availability, local demand, and transportation costs. Consuming areas may pay more for delivered oats if freight is tight or if processor demand is strong.
How US oat prices are formed
US oat prices are formed through a combination of benchmark futures and local physical market conditions. The most important concept is that there is no single “US cash oat price” that applies everywhere.
The main building blocks are:
- Futures price: the exchange-traded benchmark, mainly used for price discovery and hedging.
- Basis: the local cash adjustment versus futures, reflecting location, quality, freight, storage, and buyer demand.
- Cash bid: the actual local buying price posted by an elevator, cooperative, merchant, or processor.
- Delivered price: the price for grain delivered to a named destination, often including freight and sometimes quality terms.
- Export price: for export-oriented trade, prices may be discussed on an FOB or other shipment basis depending on the transaction chain.
For example, a futures market may rise while a local cash bid rises less, stays flat, or even falls if harvest deliveries are heavy in one region. Likewise, a processor may pay above a general elevator bid if it needs a specific quality profile or prompt nearby movement.
| Price type | Where quoted | What it means |
|---|---|---|
| CME oat futures | Exchange market | Benchmark futures price used for hedging and market reference, not the exact local farm-gate price. |
| Local cash bid | Elevator, cooperative, processor, merchant | Spot or forward purchase price at a specific location, usually adjusted by basis and quality terms. |
| Delivered price | Commercial contract | Price to a named destination, usually including transportation and delivery terms. |
| FOB export value | Export trade chain | Price at the export point before ocean freight, relevant for international trade rather than most farm sales. |
Where to check US oat prices and market information online
If you need current US oat market information, the first rule is to check the correct market for the correct purpose. A futures quote is useful for benchmarking and hedging. A local cash bid is what matters for a physical sale. Export indicators matter mostly for commercial trade flows.
Practical places to check include:
- CME Group: for oat futures and options quotations, contract months, and market details.
- USDA Agricultural Marketing Service (AMS): for grain market reports and cash market information where available.
- USDA National Agricultural Statistics Service (NASS): for acreage, production, stocks-related context, and crop progress information when published in broader reporting cycles.
- USDA Foreign Agricultural Service (FAS): for trade and international market context.
- Local elevators and cooperatives: often the best source for nearby cash bids, forward bids, and delivery terms in producing areas.
- Processors and grain merchants: especially important for food-grade oat demand, specialty quality, or direct procurement programs.
- Broker platforms and data vendors: for live futures data, spreads, options, and technical market monitoring.
Readers looking for a “live US oat price” should be careful. What is available publicly in real time is often the futures benchmark, while the physical price may only be visible through local buyer bid sheets or contracted commercial channels. That is why two farms in different states can face meaningfully different prices on the same day even when the futures market is identical.
How physical oat trading actually works in the United States
Physical oat trading in the US is mostly a merchandising and procurement business rather than an exchange-delivery business. Grain changes hands through private contracts between commercial counterparties.
Typical physical market participants
- Farmers
- Country elevators and cooperatives
- Grain merchants and trading houses
- Oat mills and food processors
- Feed mills and livestock buyers
- Exporters and importers
Common deal structures
- Spot cash sale: grain sold for nearby delivery at the buyer’s posted cash bid.
- Forward cash contract: producer and buyer lock a future delivery price in advance.
- Basis contract: futures reference and basis are managed separately.
- Hedge-to-arrive style structure: where futures may be fixed first and basis set later, if offered by the buyer.
- Delivered contract: seller commits to deliver to a specified facility or destination.
Quality matters. Oat buyers may specify test weight, moisture, foreign material, soundness, or food-grade standards depending on end use. A processor purchasing food oats will typically care more about quality consistency than a feed buyer. This can create significant price differences between otherwise similar offers.
Payment and counterparty terms also matter. Commercial sellers need to confirm delivery windows, grading standards, rejection rights, settlement timing, storage terms, and any discount schedules. In practice, a good bid is not just the highest headline price; it is the best net return after freight, shrink, dockage, and contract risk.
How futures and options are used for US oat trading
Futures and options are used in the US oat market mainly for price risk management and secondarily for speculation. They do not replace the physical trade. Instead, they provide a financial tool linked to price exposure.
The benchmark for US oats is the CME Group oat futures market. Commercial users may hedge purchases or inventory against the futures contract. Producers, merchandisers, processors, and traders may all use it differently:
- Farmers: may monitor futures as a reference and occasionally hedge if basis and local contracting tools are suitable.
- Elevators and merchants: often hedge ownership, forward purchases, and merchandising risk.
- Processors: may hedge raw material exposure while sourcing physical oats separately.
- Speculators: trade price direction, spreads, or volatility without intending to own physical grain.
Access normally comes through a futures broker or a brokerage platform. That involves account opening, margin requirements, and daily mark-to-market risk. Because leverage is involved, futures are not the same as owning grain. A trader can gain or lose financially from price movement without ever taking delivery.
Options can also be used to manage upside or downside exposure with defined premium cost, though liquidity and suitability should be assessed carefully. In a relatively smaller grain market like oats, users should always consider execution quality, bid-ask spreads, and basis risk before relying on futures alone.
| Market channel | Where it takes place | Main purpose | Key risk |
|---|---|---|---|
| Physical cash trade | Elevators, processors, merchants, farms | Move real oats from seller to buyer | Quality, freight, delivery, counterparty, local demand |
| Futures trading | CME through a broker | Hedge or speculate on benchmark price movement | Margin calls, volatility, basis mismatch |
| Options trading | CME through a broker | Manage price risk with option premium structures | Premium cost, time decay, liquidity |
Imports, exports, and logistics in the US oat market
The US oat market cannot be understood without trade flows, especially with Canada. Canadian oats are an important part of North American supply, and cross-border movement can influence processor procurement, regional basis, and supply availability in US consuming areas.
Within the United States, logistics can involve truck, rail, and commercial storage networks. In practical terms, freight often matters as much as board price. A local cash bid in a producing state may look lower than a more distant processor bid, but the delivered net may still favor the closer outlet once transportation is included.
Export activity matters most for commercial firms and larger trade participants. In those cases, price language may shift from inland cash values to delivered terminal values or export parity concepts. However, most farm-level and local merchandising decisions remain anchored to inland cash bids and basis relationships.
Main factors that drive US oat prices
US oat prices respond to both domestic and international factors. Since the market is smaller than corn or soybeans, localized shifts can have an outsized effect.
- US planting and harvest conditions: especially in key northern growing regions.
- Canadian crop conditions: crucial because of North American supply integration.
- Processor demand: food use can support regional premiums for suitable quality.
- Feed competition: oats compete with other feed grains depending on relative value.
- Freight and rail conditions: transportation constraints can widen regional price gaps.
- Stocks and storage: tight nearby supply can strengthen basis even if futures are quiet.
- Currency effects: especially relevant for cross-border trade competitiveness.
- Weather: quality as well as yield matters in oats.
Forecasting should therefore be approached as a set of scenarios rather than a single prediction. A larger crop in North America can pressure nearby cash values if demand does not expand at the same pace. A weather problem, quality issue, or logistics disruption can tighten available milling-quality supply and support basis levels even when the broader grain complex is mixed.
Practical trading approach for farmers, merchants, and investors
A practical US oat trading plan starts by deciding which market you are actually participating in.
For physical sellers and buyers
- Identify the most relevant local buyers: elevator, cooperative, processor, feed buyer, or merchant.
- Compare bids on the same basis: same location, same delivery window, same quality assumptions.
- Ask whether the bid is spot, forward, delivered, or basis-only.
- Review moisture, test weight, and quality discounts before committing.
- Calculate net price after freight and any on-farm loading or storage cost.
- Check counterparty reliability and payment timing.
For futures and options users
- Use the CME oat contract as a benchmark, not as a substitute for local cash discovery.
- Understand basis risk: a hedge can reduce futures exposure but not eliminate local cash divergence.
- Know contract month exposure and expiry timing.
- Plan margin liquidity before entering a futures hedge.
- Use options where suitable if flexibility matters more than fully locking a price.
In other words, online trading tools are best for benchmarking and risk management, while the physical market determines where grain actually moves and what the final commercial settlement looks like.
Frequently asked questions
Where can I check the current US oat futures price?
The main benchmark is the CME Group oat futures market. That is the correct place to check the exchange-traded reference price, contract months, and related market information.
Where can I find local US cash oat bids?
The most practical sources are local elevators, cooperatives, grain merchants, and processors. USDA AMS market reports may also provide useful cash-market context where available, but local buyer bid sheets are usually more relevant for an actual sale.
Is the CME oat price the same as the farm-gate oat price?
No. The CME price is a futures benchmark. Farm-gate or elevator cash prices differ because of basis, freight, quality, timing, storage, and local buyer competition.
What unit is used in US oat trading?
US oat futures are commonly discussed in cents per bushel, while physical transactions may also be discussed in dollars per bushel or dollars per ton depending on the contract and buyer. Always confirm the unit before comparing offers.
How are oats usually sold physically in the United States?
Most oats are sold through private commercial channels such as elevators, cooperatives, merchants, processors, and feed buyers. Sales can be spot, forward, delivered, or structured with basis and futures components.
Can individual traders buy and sell oat futures online?
Yes, typically through a regulated futures broker or brokerage platform. But this is financial exposure, not the same as owning physical oats, and it involves leverage and margin risk.
Why does Canadian supply matter for US oat prices?
The US market is closely linked to Canadian oat production and trade. Cross-border supply affects processor procurement, regional availability, and price relationships in North America.
What most often moves US oat prices?
The main drivers are North American crop conditions, processor demand, feed competition, quality, stocks, freight, and basis behavior in key producing and consuming regions.
Sources
- CME Group
- USDA Agricultural Marketing Service
- USDA National Agricultural Statistics Service